There was a time when submitting a tax return largely meant telling SARS what happened during the year.
That relationship is changing.
Increasingly, SARS may already have a substantial amount of information about a taxpayer before a return is submitted.
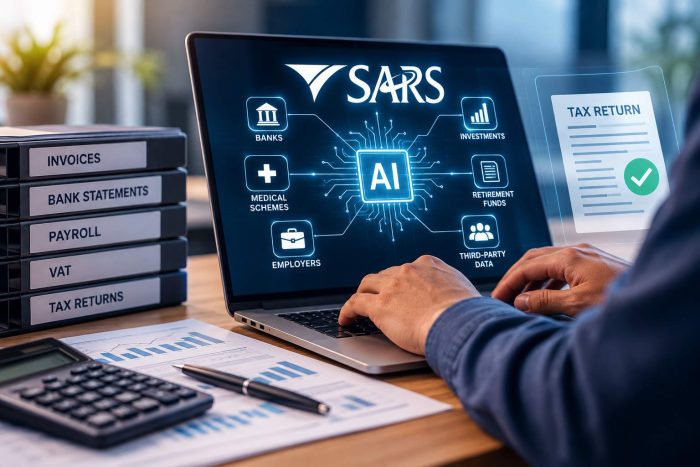
During the 2026 Filing Season, SARS confirmed that its Auto Assessments are being driven by expanded third-party data sources, while its broader technology strategy includes artificial intelligence, big data and increasingly sophisticated risk profiling.
For taxpayers and business owners, this creates an important change in mindset:
Tax compliance is increasingly about making sure that your records agree with information SARS may already have.
Where does SARS get its information?
SARS receives information from a growing range of third parties.
These include employers, banks, financial institutions, medical schemes, retirement fund administrators and other organisations required to report information to SARS.
The information can include interest earned, investment transactions, medical information, retirement contributions and employment income.
SARS specifically states that third-party data is used to pre-populate returns, verify taxpayer declarations and identify discrepancies or risks.
That means simply leaving something off a return does not necessarily mean SARS will not know about it.
The rise of the Auto Assessment
Auto Assessments are perhaps the most visible example of this change.
SARS expected more than six million taxpayers to receive Auto Assessments during the 2026 Filing Season. The assessments use information obtained from employers, banks, medical schemes, retirement funds and other third parties.
For many taxpayers, this is extremely convenient.
But an Auto Assessment should not automatically be interpreted as confirmation that every piece of information is correct.
The taxpayer should still consider whether the information used by SARS properly reflects his or her actual tax position.
There may, for example, be income, deductions or circumstances that SARS does not have sufficient information to identify automatically.
What happens when information does not match?
This is where proper accounting and tax administration become increasingly important.
Imagine that your accounting records show one amount, your VAT declarations imply another, payroll information submitted to SARS shows something different again, and banking or third-party information points in yet another direction.
None of those differences automatically means that anything improper has occurred.
There may be legitimate explanations.
The problem arises when nobody has identified the difference or can explain it.
As SARS becomes more data-driven, inconsistencies can become increasingly visible.
Small businesses should pay particular attention
Small businesses often develop their accounting systems gradually.
A business may begin with a spreadsheet, move to accounting software later, use different systems for payroll and invoicing, and perhaps have information spread between bank accounts, payment gateways and online marketplaces.
That can work operationally.
From a tax perspective, however, the information eventually needs to tell a consistent story.
Turnover recorded in the accounting system should make sense compared with bank deposits and sales records.
VAT returns should be supported by appropriate documentation.
Payroll declarations should reconcile with payroll records.
Expenses claimed should have supporting evidence.
And financial statements and income-tax returns should ultimately be based on reliable accounting records.
SARS is moving towards more automated risk profiling
SARS’s 2026/27 Annual Performance Plan provides an indication of where tax administration is heading.
It refers to the use of big data, Agentic AI and a move from declaration-based processes towards more real-time risk profiling and case selection.
This does not mean that every discrepancy automatically results in an audit.
It does mean that maintaining accurate records is becoming increasingly important.
Good bookkeeping is becoming part of tax risk management
Bookkeeping is sometimes treated as little more than capturing invoices and bank transactions.
That view is becoming outdated.
Good bookkeeping creates the underlying evidence supporting what is eventually declared to SARS.
South African taxpayers are generally required to retain relevant records for five years, and records may need to be retained for longer where an audit, investigation, objection or appeal remains unresolved.
Good records therefore do more than produce financial statements.
They allow a taxpayer to explain how a number was calculated if SARS asks questions months or even years later.
Compliance should happen before SARS asks questions
One of the most effective approaches to tax compliance is to identify problems before a return is submitted.
At AGBS Financial, we believe accounting and tax compliance should work together.
That means looking for unexplained differences, incomplete records, and potential compliance problems before they become SARS queries.
Modern tax administration is increasingly data-driven.
Your accounting records should be ready for that reality.